lambda=0.9;p=0.2;mu=1/p;sigma2=(1-p)/p^2
m1=mu*lambda*50;m2=(sigma2+mu^2)*lambda*50
1-pnorm(250,225,sqrt(m2))
[1] 0.2892574\[ Var(X) =E[Var(X|Y)]+Var[E(X|Y)] \]
Proof: The variance can be decomposed into expected values as follows: \[ \operatorname{Var}(X)=\mathrm{E}\left(X^2\right)-\mathrm{E}(X)^2 . \]
This can be rearranged into: \[ \mathrm{E}\left(Y^2\right)=\operatorname{Var}(Y)+\mathrm{E}(Y)^2 . \]
Applying the law of total expectation, we have: \[ \mathrm{E}\left(Y^2\right)=\mathrm{E}\left[\operatorname{Var}(Y \mid X)+\mathrm{E}(Y \mid X)^2\right] . \]
Now subtract the second term from (2): \[ \mathrm{E}\left(X^2\right)-\mathrm{E}(X)^2=\mathrm{E}\left[\operatorname{Var}(X \mid Y)+\mathrm{E}(X \mid Y)^2\right]-\mathrm{E}(X)^2 . \]
Again applying the law of total expectation, we have: \[ \mathrm{E}\left[\operatorname{Var}(X \mid Y)+\mathrm{E}(X \mid Y)^2\right]-\mathrm{E}[\mathrm{E}(X \mid Y)]^2 . \]
With the linearity of the expected value, the terms can be regrouped to give: \[ \mathrm{E}[\operatorname{Var}(X \mid Y)]+\left(\mathrm{E}\left[\mathrm{E}(X \mid Y)^2\right]-\mathrm{E}[\mathrm{E}(X \mid Y)]^2\right) . \]
Using the decomposition of variance into expected values, we finally have: \[ \operatorname{Var}(X)=\mathrm{E}[\operatorname{Var}(X \mid Y)]+\operatorname{Var}[\mathrm{E}(X \mid Y)] \]
\[ Z(t) = \sum_{k=1}^{X(t)}Y_k \]
Take its exptcation:
\[ E[Z(t)]= E[E[Z(t)|X(t)]]=E[\mu X(t)]= \mu\lambda t \]
And its variance:
\[ Var[Z(t)]=E[Var[Z(t)|X(t)]] + Var[E(Z(t)|X(t))] \]
Used the Law of total Variance, and sub in previous result \(E(Z(t)|X(t))=\mu X(t)\)
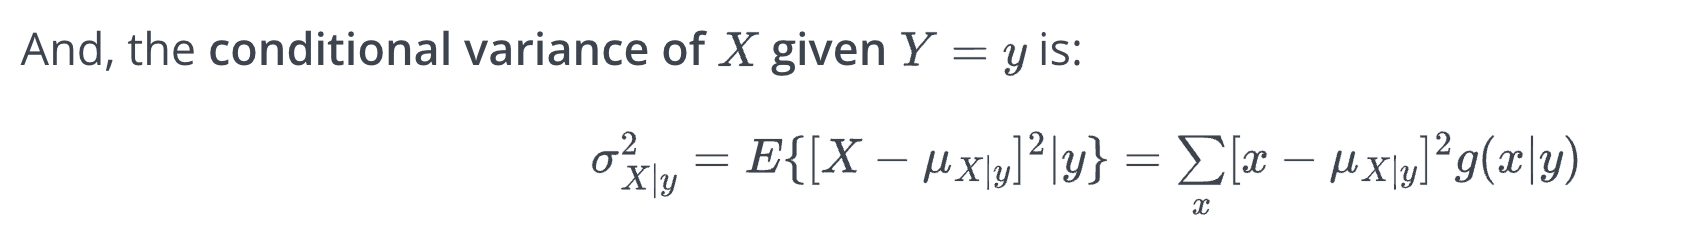
hence the result goes to
\[ E[\sigma^2X(t)] + Var[\mu X(t)]= \sigma ^2 \lambda + \mu^2 \sigma^2 \]
Note: use MGF + Law of toal expectation can reach the same result but it’s easier beyond 3rd moment
Aftershocks constitute the greatest proportion of shocks in
an earthquake catalog。
\(Z(t)=\sum_{k=1}^{X(t)} Y_k\), for \(t \geq 0\), where \(X(t)\) is a homogeneous Poisson process with \(\lambda=0.9\) (year) and \(Y\) has a geometric distribution with parameter \(p=0.2\), mean \(\mu=1 / p\), and variance \(\sigma^2=(1-p) / p^2\). Note that \(E[Z(t)]=\mu \lambda t\) and \(\operatorname{Var}[Z(t)]=\left(\sigma^2+\mu^2\right) \lambda t\). Find the approximate probability that at least 100 aftershocks within the next 50 years.
lambda=0.9;p=0.2;mu=1/p;sigma2=(1-p)/p^2
m1=mu*lambda*50;m2=(sigma2+mu^2)*lambda*50
1-pnorm(250,225,sqrt(m2))[1] 0.2892574Taking mean on the shocks
Method of moment
Suppose that families migrate to an area at a Poisson rate \(\lambda=2\) per week. Find the approximate probability that at least 240 people migrate to the area within the next 50 weeks.
\[ E[X(50)]= \lambda * 50 *E(Y_i) = 2*50 *5/2 \]
The number of hours between successive train arrivals (T ) at the station is uniformly distributed on (0, 1).Passengers arrived according to a Poisson process with rate 7 per hour. Suppose a train has just left the station. Let X denote the number of people who get on the next train. Find \(E(X) ,Var(X)\)
\[E(X) = E(E(X|T)) = E(7T(t)) = 0.5*7\]
\[ Var(X)= E(Var[X|T])+Var[E(X|T)] \]
Simplifies:
\[ RHS= E(Var[X|T])+ 49Var[T] = 7*\frac{1}{2}+ \frac{49}{12} \]